Business
Navia Benefits: Accounts, Card, Claims & Login

A benefits card arrives in the mail, an account appears in an employee portal, or a claim asks for a receipt—and suddenly a workplace benefit feels more complicated than helpful. If you searched for “navia benefits,” you likely want to know what Navia is, which expenses your account can cover, how to sign in, and what to do when a payment or reimbursement does not go as expected. This guide answers those practical questions and explains how to use Navia Benefit Solutions without confusing the administrator with the employer-sponsored plan itself.
Navia Benefit Solutions administers a range of employee benefit programs for participating employers and organizations. Depending on the plan your employer offers, your Navia account may involve a health care flexible spending account (FSA), dependent care FSA, health savings account (HSA), health reimbursement arrangement (HRA), commuter benefits, a lifestyle spending account, education benefits, or another service. Not every participant has every account, and the rules can differ by employer, plan document, and benefit type.
The most useful starting point is simple: identify the exact account listed in your Navia portal, read its plan rules, and check eligibility before spending or submitting a claim. Navia’s official participant resources provide account access, eligible-expense guidance, card instructions, mobile-app details, and support contacts. This article explains how those tools fit together, how to avoid common mistakes, and what records to keep. It is general information, not a guarantee that a particular purchase qualifies or tax advice for your individual circumstances.
Search intent: informational and navigational. Readers are generally trying to understand Navia benefits and reach the right account, card, claim, or support resource.
What are Navia benefits?
Navia Benefit Solutions is a benefits administrator that helps participating employers manage benefit programs and gives participants tools to access the benefits made available through their workplace or plan sponsor. Navia is not a single universal benefit with one fixed balance or one set of spending rules. The benefit you can use depends on the specific account in which you are enrolled and the rules governing that account.
For participants, the official Navia website brings together benefit explanations, account access, mobile tools, card guidance, eligible-expense information, and help resources. The MyNavia mobile app is described by Navia as available at no charge to participants with an FSA, HRA, HSA, or commuter benefit. Features include viewing balances, submitting claims, receiving claim alerts, and checking eligible expenses.
Start with the participant page at https://www.naviabenefits.com/participants/ and follow the link that matches your benefit. If your employer gave you a separate plan website or enrollment guide, use that as well; employer-specific rules can determine deadlines, funding, carryover, and which features are available.
Which Navia benefits might be available to you?
Navia lists several benefit categories, but your employer chooses which ones to offer. The table below is a high-level orientation; it is not a substitute for your plan documents or a confirmation that you are enrolled.
| Benefit type | Typical purpose | Important point to verify |
| Health Care FSA | Pay eligible out-of-pocket health care expenses using an elected account. | Annual election, eligible expenses, substantiation rules, and any carryover or grace-period provisions. |
| Dependent Care FSA / DCAP | Pay eligible care expenses that allow you or your spouse to work or look for work, subject to plan and tax rules. | Qualifying dependents, qualifying care, annual limits, and claim deadlines. |
| Health Savings Account (HSA) | Save and pay for qualified medical expenses when eligible for an HSA. | HSA eligibility, contribution rules, tax treatment, and recordkeeping obligations. |
| Health Reimbursement Arrangement (HRA) | Receive reimbursement for expenses defined by the employer’s HRA plan. | Covered services, reimbursement limits, whether a card is enabled, and claim documentation. |
| Commuter benefits / GoNavia | Use eligible benefit funds for qualifying transit or parking expenses where offered. | Which transit or parking costs qualify, funding availability, and local rules. |
| Lifestyle or education benefits | Use employer-provided funds for plan-approved lifestyle, tuition, or student-loan-related expenses. | The employer’s approved expense list, maximums, and proof required. |
How do Navia benefits save you money?
The potential value comes from using the benefit your employer has made available in the way its rules allow. Some accounts let employees set aside salary before certain taxes are calculated; others reimburse eligible costs from employer-funded funds. The tax treatment and eligibility requirements are different across FSAs, HSAs, HRAs, commuter programs, and lifestyle or education accounts.
For example, a worker who regularly pays eligible dental, vision, or prescription costs may find a health care FSA useful if the employer offers one. A worker who pays for qualifying dependent care may want to review a dependent care account. Someone with regular public-transit or eligible parking expenses may benefit from a commuter program. These are examples, not universal promises: the plan must cover the account and the expense must meet the applicable rules.
Do not assume that every account produces the same tax savings, that every contribution is employer-funded, or that all unused money carries forward. The federal tax treatment of an HSA differs from an FSA, and HRA availability depends on the employer’s plan. Review current IRS guidance and your plan documents before choosing contributions or making a tax-related decision.
How to sign in to your Navia benefits account
Use the official Navia participant portal rather than a link from an unexpected text message or email. Navia’s participant resources include a registration and login pathway, and its official portal provides account information and claim tools.
Open the official participant page at https://www.naviabenefits.com/participants/ or the portal link supplied by your employer.
Choose the registration or login option. If you are new, follow the registration process and provide only the information the official site requests.
Complete any email or text verification steps shown during setup.
Once signed in, open the relevant benefit from the account or “My Benefits” area. Check the account name before reviewing balances or submitting a claim.
Save the official portal as a bookmark on your personal device if appropriate, and avoid signing in on shared or public computers.
If you cannot register, confirm that your employer or plan sponsor has provided the correct eligibility details and that you are using the right portal. A portal login is separate from the underlying benefit account, so successfully creating a username does not itself establish eligibility for a particular plan.
What can you use the Navia Benefits Card for?
The Navia Benefits Card is a payment card that can draw from eligible benefit funds when the particular plan and transaction support card use. It is not a general-purpose allowance for any purchase. Navia explains that card acceptance depends on the benefit type, merchant setup, and the expense being paid. The official card page describes use at certain health care providers and participating merchants, and commuter card use at eligible transit or parking locations.
Some merchants use an Inventory Information Approval System (IIAS) to identify eligible products at checkout. At other merchants, a transaction may require additional documentation. A card swipe therefore does not always mean the purchase has been finally approved under the plan. Keep itemized records and respond to documentation requests.
| Account or benefit | Potential card use described by Navia | What to watch for |
| Health Care FSA | Eligible purchases at participating health care merchants and providers. | A transaction may need documentation; ineligible items can be declined or require repayment. |
| HRA | Eligible purchases if the employer’s HRA is configured for card access. | The plan defines covered expenses and reimbursement conditions. |
| HSA | Qualified medical expenses at supported merchants and providers. | Keep tax records and receipts even when the card payment itself does not require submission. |
| Commuter benefit | Eligible transit or parking payments at supported authorities, websites, kiosks, lots, or garages. | Confirm the expense category and available balance before paying. |
Navia also says eligible participants may be able to add the card to Apple Pay or Google Pay. Availability can depend on the card and account. See the official instructions at https://www.naviabenefits.com/participants/resources/benefits-card/ rather than assuming every digital wallet or merchant is supported.
How to submit a claim and track reimbursement
If you paid for an eligible expense yourself, your plan may let you submit a claim for reimbursement. The available process depends on the account and plan. Navia’s mobile app supports claim submission, including submitting a receipt image, and the participant portal provides access to claim information.
Confirm the expense is eligible under your specific benefit and that the service or purchase date falls within the plan’s rules.
Gather an itemized statement, bill, receipt, or Explanation of Benefits (EOB), as applicable. Documentation should show details such as the date, provider or merchant, service or item, and cost.
Sign in to the Navia portal or MyNavia app and choose the correct benefit account.
Enter the claim details carefully and upload readable supporting documentation in the requested format.
Check the claim status in the portal and respond promptly if Navia asks for more information.
A payment-card receipt alone may not prove what service was received or whether it qualifies. Navia’s portal help explains that itemized bills and EOBs can be appropriate substantiation, while cancelled checks or a generic credit-card receipt may not contain enough detail. Follow the exact documentation instructions for your claim type.
How to check eligible expenses before spending
Eligibility is one of the most important details to verify because similar-looking purchases can receive different treatment depending on the account. Navia offers eligible-expense resources and benefit-specific guidance. Check the account category first, then look up the item or service, and save the supporting documentation.
For a health care FSA or HSA, confirm that the item or service qualifies under the applicable medical-expense rules.
For a limited-purpose FSA, check whether the account is restricted to categories such as eligible dental and vision expenses.
For a dependent care account, verify that the care and dependent meet the program’s requirements; ordinary household expenses do not automatically qualify.
For commuter benefits, confirm whether the expense is qualifying transit or parking rather than a general travel cost.
For lifestyle and education accounts, use the employer’s approved list because eligible categories can be specific to that plan.
When a purchase is unclear, ask Navia or your plan administrator before paying from the account. This is especially useful for mixed-purpose purchases, subscriptions, bundled services, or expenses that span more than one benefit category.
Navia benefits versus the underlying plan: what is the difference?
A common source of confusion is treating the administrator, the account, and the employer’s health insurance as if they were the same thing. They are not. Navia provides administration and tools for certain benefit programs. Your employer or plan sponsor determines which programs are offered, and the plan documents set the applicable rules. A Navia account should not automatically be interpreted as health insurance or as a replacement for insurance coverage.
| Term | Meaning | Who or what sets the rules? |
| Navia Benefit Solutions | Administrator and participant service platform for offered benefits. | Navia handles services within the arrangement; the plan sponsor sets plan-specific choices. |
| Benefit account | The FSA, HSA, HRA, commuter, or other account shown in your portal. | The applicable law and the plan or account terms. |
| Employer / plan sponsor | The organization offering or sponsoring the benefit. | Selects available programs and establishes plan provisions where permitted. |
| Health insurance plan | Coverage for medical services under an insurance policy or health plan. | The insurer or plan documents; a Navia spending account is a different arrangement. |
Common Navia benefits problems and how to handle them
Why was my Navia Benefits Card declined?
Navia’s portal help lists several possible causes: the card may not be activated, the available balance may be insufficient, a prior transaction may be awaiting substantiation, the merchant may not be approved for the transaction, or the merchant may have entered card details incorrectly. Check your balance and transaction history, confirm the merchant and expense are eligible, and review any request for supporting documentation. If the problem persists, contact Navia through the official participant support channel.
Why is my claim pending or denied?
A claim may need additional documentation, may fall outside the plan’s eligibility rules, or may not meet a deadline. Read the status message carefully and compare the request with your plan’s requirements. If the explanation is unclear, contact participant support with the claim reference and the date submitted. Do not send unnecessary sensitive information in an ordinary email.
What if I lost my card?
Use the official portal or contact Navia to report a lost or stolen card and request a replacement. Navia’s benefits-card page says replacement card requests have no fee. Until the issue is resolved, review your account activity and report any transactions you do not recognize.
What if I changed jobs or my plan year is ending?
Do not assume that funds, cards, or claim deadlines work the same way across accounts. FSA carryover, grace periods, HSA ownership, HRA availability, and commuter funds can follow different rules. Review the plan’s termination and year-end notices, identify the final date for eligible expenses and claim filing, and contact the plan administrator if your employment or coverage changes.
Practical checklist: make the most of Navia benefits
Use this checklist during enrollment and whenever you plan to spend or submit a claim.
Identify every benefit account actually offered to you and read the current plan guide.
Record your contribution election, employer funding, plan year, and any important deadlines.
Check eligible expenses before purchase, not only after a card is declined.
Use the correct account when submitting a claim and upload itemized proof.
Review balances, card transactions, and claim statuses regularly.
Keep records for tax reporting and future questions, especially for HSA expenses.
Use only official Navia links and contact channels for account access and support.
A small routine can prevent avoidable frustration: check your balance before a large purchase, save the itemized receipt immediately, and review your account after the transaction. For claims, make a note of the submission date and revisit the status until the matter is resolved.
Where can you get official Navia benefits help?
Start with Navia’s participant resources at https://www.naviabenefits.com/participants/ for benefit descriptions and self-service tools. For card questions, use https://www.naviabenefits.com/participants/resources/benefits-card/. For app instructions, visit https://www.naviabenefits.com/participants/resources/mynavia-app/.
Navia’s contact page lists participant support for FSA, HSA, HRA, and commuter participants at 1-800-669-3539, Monday through Friday, 5 a.m. to 5 p.m. Pacific Time; it also lists 425-452-3500 and email options. Check the current contact page before calling because hours and contact details can change: https://www.naviabenefits.com/contact/. Have your account or claim details available, but share sensitive information only through verified channels.
Conclusion: focus on your specific Navia account
Navia benefits can make employer-sponsored spending accounts and reimbursements easier to manage, but the value depends on knowing which benefit you have and following its rules. Start at the official participant portal, confirm your account type, check eligible expenses, and keep itemized records. Use the debit card only for qualifying expenses, track claims through the portal or app, and contact participant support when a plan rule or transaction is unclear. The most reliable answer for any particular purchase is the current plan document paired with Navia’s official account-specific guidance.
Frequently asked questions about Navia benefits
Is Navia Benefits a health insurance company?
Navia Benefit Solutions administers workplace benefit programs; a Navia spending account is not automatically the same as a health insurance policy. Check your insurance documents separately for coverage and provider-network questions.
Can I use the Navia Benefits Card anywhere Mastercard is accepted?
No. Acceptance depends on the benefit account, merchant setup, transaction type, and plan rules. A merchant accepting Mastercard does not make every purchase eligible.
Does the MyNavia app cost money?
Navia describes the MyNavia app as free to download and use for participants with an FSA, HRA, HSA, or commuter benefit. Your mobile carrier may still charge for data use.
Do I need to keep receipts if I used the Navia card?
Keep itemized receipts and supporting records. Some transactions may be automatically verified, but other account types or purchases can require documentation. HSA users should retain records for tax purposes even when the card transaction does not require submission.
Can unused Navia FSA money roll over to the next year?
It depends on the employer’s plan and the rules that apply to that FSA. Carryover or a grace period may be available in some plans, but you should not assume either feature applies to your account.
How do I contact Navia about a missing reimbursement?
Sign in to the official portal to review the claim status and any documentation requests, then use the current participant support details on Navia’s official contact page. Keep your claim reference and submission date handy.
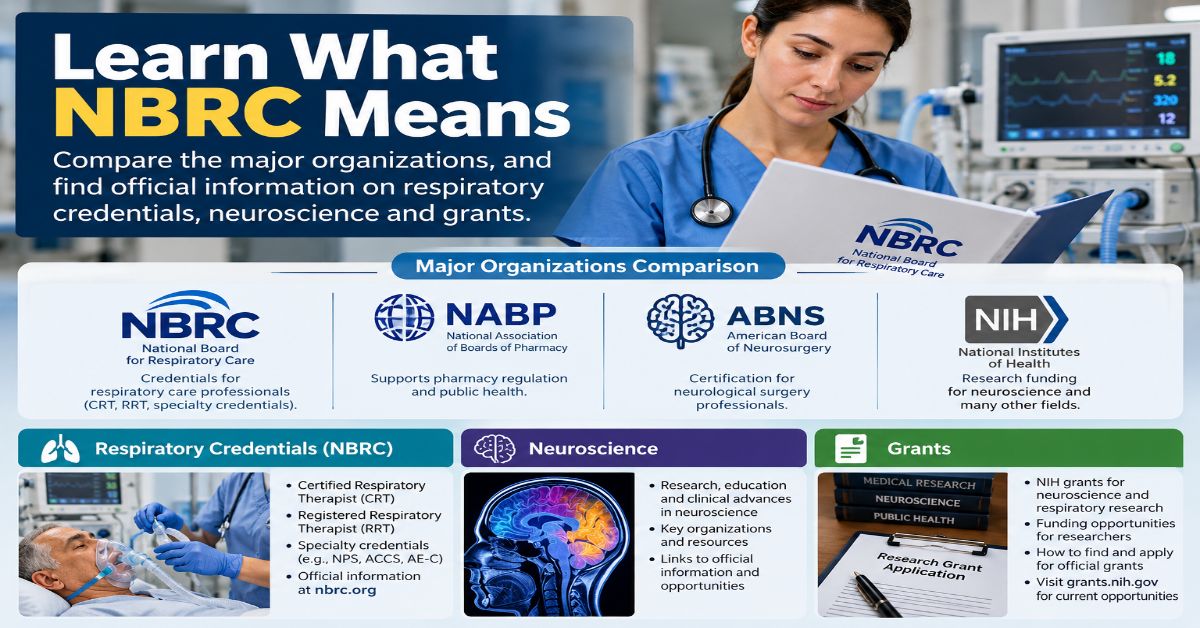
A search for “NBRC” can lead to very different destinations: a respiratory-care credentialing body in the United States, a neuroscience research institute in India, or a regional economic-development commission serving four U.S. states. If you landed on a page that does not match your goal, the problem may not be your search—it may be that the same four letters are used by several organizations.
NBRC does not have one universal meaning. The right interpretation depends on context, including whether you are researching respiratory therapy exams and credentials, brain research and academic programs, or grants for rural communities in the northern United States. This guide distinguishes the major organizations using the acronym, explains what each does, and shows how to verify that you are using the official website before relying on application instructions, deadlines, or eligibility details.
The quickest way to identify the right NBRC is to look at the surrounding terms in your search. Words such as CRT, RRT, respiratory therapist, or credential maintenance point toward the National Board for Respiratory Care. Terms such as neuroscience, Manesar, research, or doctoral study point toward India’s National Brain Research Centre. References to Catalyst grants, rural infrastructure, Maine, New Hampshire, New York, or Vermont point toward the Northern Border Regional Commission. The sections below cover these uses separately so readers can act on the information that fits their needs.
Because acronyms overlap, this article treats each organization as a distinct entity rather than assuming one meaning applies to everyone. Official websites are linked in the relevant sections; program rules and dates should always be checked there because they can change.
What does NBRC stand for?
NBRC is an acronym used by multiple organizations. Three prominent meanings are the National Board for Respiratory Care in the United States, the National Brain Research Centre in India, and the Northern Border Regional Commission in the United States. Their purposes are unrelated, so a reader should confirm the organization before following instructions or citing information.
This comparison helps match common search clues to the correct organization.
| NBRC name | Main purpose | Useful search clues |
| National Board for Respiratory Care | Credentials and examinations for respiratory-care professionals | CRT, RRT, respiratory therapist, exam |
| National Brain Research Centre | Neuroscience research and education in India | brain research, neuroscience, Manesar |
| Northern Border Regional Commission | Economic development funding in designated counties across four U.S. states | grants, rural infrastructure, Catalyst Program |
1. National Board for Respiratory Care: NBRC credentials and exams
The National Board for Respiratory Care (NBRC) is a U.S. not-for-profit credentialing organization focused on respiratory care. Its mission is to promote excellence in the profession by awarding credentials based on demonstrated competence. It develops credentialing examinations and offers credentials for respiratory therapists and pulmonary-function professionals, along with specialty credentials for qualified practitioners.
The organization is relevant to people preparing for respiratory-care examinations, professionals checking credential requirements, educators advising students, and employers seeking to understand professional qualifications. NBRC credentials are not the same thing as a college degree: education provides the foundation, while an examination and the applicable credentialing rules establish whether a candidate has met a defined competency standard.
Which respiratory-care credentials does NBRC offer?
The NBRC website lists several credentials, including Certified Respiratory Therapist (CRT), Registered Respiratory Therapist (RRT), Certified Pulmonary Function Technologist (CPFT), Registered Pulmonary Function Technologist (RPFT), and specialty credentials. Specialty areas include adult critical care, neonatal and pediatric care, sleep disorders, and asthma education. Credential names and eligibility requirements should be confirmed on the official NBRC site before making an exam plan.
The distinction between a general credential and a specialty credential matters. Entry-level credentials establish a professional foundation; specialty credentials are intended to recognize additional knowledge in a defined area. A candidate should not assume that every specialty exam is available immediately after graduation or that the eligibility requirements are identical across credentials.
How should candidates approach an NBRC exam?
Candidates should begin with the official examination page for the exact credential they want. Exam names, eligibility rules, content outlines, fees, scheduling arrangements, and maintenance requirements may differ. The NBRC works with PSI for examination administration, so official candidate instructions should take precedence over informal posts, outdated study guides, or third-party summaries.
Identify the exact credential and read its current eligibility requirements.
Review the official content outline and any candidate handbook linked from the credential page.
Confirm how the examination is scheduled, what identification is required, and which policies apply on test day.
Use reputable study materials that match the current exam outline, and build practice around the skills and concepts named there.
After passing, review the credential-maintenance rules and keep personal contact details current.
A practical example: someone searching “NBRC RRT exam” is probably not looking for a brain-research institute or a grant commission. They need the respiratory-care credential pathway, the current exam requirements, and the relevant candidate resources.
Where can readers verify NBRC respiratory-care information?
Start with the official website: https://www.nbrc.org/. Its candidate resources, credential pages, and contact information are the best starting points for current rules. For questions that are not answered online, the organization publishes its executive-office contact details on its official contact page: https://www.nbrc.org/contact/. Avoid sharing personal information or payment details through unofficial accounts that merely use the NBRC name.
2. National Brain Research Centre: NBRC in India
The National Brain Research Centre (NBRC) is an Indian institute dedicated to neuroscience research and education. It is located in Manesar, Haryana, and is an autonomous institute supported by India’s Department of Biotechnology; it also has deemed-university status. Its work brings together researchers from fields such as biology, computation, mathematics, physics, and engineering to study the brain and nervous system.
This NBRC is relevant to prospective research students, scientists, academic collaborators, and readers seeking reliable information about neuroscience projects. It is not the U.S. respiratory-care credentialing body and does not administer the NBRC respiratory-therapy examinations.
What does the National Brain Research Centre study?
Neuroscience investigates the structure and function of the nervous system, including how people sense, learn, remember, move, and respond to the world. NBRC describes research across cellular and molecular neuroscience, systems neuroscience, cognitive neuroscience, computational neuroscience, and translational neuroscience. These areas range from studying mechanisms inside individual cells to investigating cognition and developing approaches that may eventually improve understanding of neurological disorders.
The institute’s research themes include brain function in health and disease, sensory processes, learning and memory, and disorders affecting the nervous system. Such research is multidisciplinary: a project may combine biological experiments with mathematical modelling, computational analysis, imaging, or clinical collaboration. That breadth is one reason the institute may interest students from different academic backgrounds.
How can a prospective student or researcher use NBRC’s website?
A prospective applicant should first identify whether the goal is a degree, a research position, a short course, or collaboration. The entry route and required qualifications can differ. Check the institute’s current admissions announcements, faculty and research pages, and official notices rather than relying on a cached search snippet or an old social-media post.
For study: verify the current programme, eligibility, application dates, selection process, and required documents.
For research: review faculty interests and research divisions, then follow the institute’s official process for contacting a group or applying for a position.
For events and training: check the current notices for dates, registration rules, and whether the event is open to external participants.
Official starting points include the institute’s profile on the Indian government’s BRIC website at https://www.bric.nic.in/institutes/nbrc/ and the Government of India’s India Science, Technology & Innovation portal at https://www.indiascienceandtechnology.gov.in/organisationsdbt/national-brain-research-centre-nbrc. These sources identify the institution and describe its research and educational role.
3. Northern Border Regional Commission: NBRC grants and economic development
The Northern Border Regional Commission is a federal-state partnership supporting economic and community development in designated counties in Maine, New Hampshire, New York, and Vermont. Created by Congress in 2008, the commission directs resources toward regional strategies and projects intended to strengthen economic opportunity and community vitality. It is the relevant NBRC for local governments, eligible organizations, community-development groups, and other applicants exploring regional funding.
Unlike the National Board for Respiratory Care, this NBRC is not a credentialing organization. Unlike the National Brain Research Centre, it is not a neuroscience institute. The strongest clues are references to grant applications, eligible counties, infrastructure, workforce development, rural economies, or the commission’s named funding programmes.
What kinds of projects may NBRC support?
The commission’s programmes are designed to address economic and community-development needs in its service area. Programme priorities and eligible costs vary, but applicants may encounter themes such as infrastructure, workforce capacity, business and industry development, and projects that strengthen regional economic resilience. A project’s general usefulness is not enough to establish eligibility: the applicant type, location, programme objectives, match requirements, and application stage all matter.
The NBRC has described programmes including the Catalyst Program, Forest Economy Program, and Timber for Transit Program. The active portfolio, application windows, funding availability, and rules can change from year to year. Therefore, an article or government page from a previous funding cycle should be treated as background rather than proof that a programme is currently open.
How does an organization start an NBRC grant application?
The commission’s applicant resources explain that pre-applications are required for its grant programmes. A pre-application is not the same as a full application: an organization must follow the commission’s process and receive an invitation to apply before submitting a full application through its Grants Management System, where applicable.
Confirm that the proposed project and applicant are located within the programme’s eligible area and fit the current programme rules.
Read the current funding notice, applicant guidance, and programme-specific requirements from the official NBRC website.
Register or update the organization’s account and authorized contacts in the Grants Management System as directed.
Prepare the required pre-application and supporting information, paying attention to project scope, budget, outcomes, partnerships, and any match requirements.
Submit through the designated system and retain confirmation records. Do not assume that downloading a blank form or emailing it separately counts as submission.
The commission’s applicant-resources page is the key starting point: https://www.nbrc.gov/applicant-resources. Its official overview is at https://www.nbrc.gov/about-nbrc. Applicants should use these pages for the current process and deadlines, not rely on a third-party list that may describe a previous year’s programme.
How can you tell which NBRC you need?
Use the context around the acronym rather than the letters alone. This table maps common searches to the most likely organization and the next useful action.
| If your search mentions… | Likely NBRC | Best next step |
| CRT, RRT, respiratory therapy, exam eligibility | National Board for Respiratory Care | Open the credential or candidate page at nbrc.org |
| Neuroscience, brain research, Manesar, PhD | National Brain Research Centre | Check official institute admissions and research notices |
| Catalyst, grant, eligible counties, rural development | Northern Border Regional Commission | Read current programme guidance and applicant resources |
| Only “NBRC,” with no other context | Ambiguous | Add a location, profession, programme, or goal to the search |
Common mistakes to avoid when researching NBRC
Assuming the acronym identifies one organization
The most common mistake is treating the first search result as the only possible meaning. Check the full organization name, country, official domain, and purpose before acting. A credentialing rule from the U.S. respiratory-care organization will not answer a question about Indian neuroscience admissions or regional grants.
Relying on old deadlines or third-party summaries
Exam rules, academic admissions, and grant cycles are all time-sensitive. A page may remain visible after its deadline has passed. Look for a current date, programme year, official notice, or candidate handbook, and confirm important requirements directly with the organization.
Confusing a credential, an academic qualification, and a grant
These are different kinds of institutional activity. A professional credential records that a person has met a competency standard; an academic programme provides education or research training; a grant programme allocates funding under defined eligibility and selection rules. The shared acronym does not make their processes interchangeable.
Treating search snippets as complete instructions
Search-result summaries can omit exceptions, eligibility conditions, or later updates. Use snippets to identify the likely page, then read the official source itself. Before paying a fee, submitting sensitive documents, or committing project resources, confirm that the destination is an official channel.
A quick verification checklist
Before using any NBRC information, check these five details:
Full name: Does the page spell out the organization’s complete name?
Location: Does the country, state, or city match your intended organization?
Purpose: Is the page about credentials, neuroscience, or economic-development funding?
Date: Are the deadline, exam rules, or programme requirements current?
Official source: Is the information published by the organization or a relevant government agency?
This checklist is simple, but it prevents a costly category error—such as preparing for the wrong examination, contacting an unrelated institute, or using a grant form from a past funding cycle.
Conclusion: Start with the full name, not just NBRC
NBRC is a useful search term only when paired with the right context. The National Board for Respiratory Care supports professional credentialing in respiratory care; India’s National Brain Research Centre advances neuroscience research and education; and the Northern Border Regional Commission supports economic development in designated communities across four U.S. states. Each serves a different audience and has its own official procedures.
For the fastest route to an accurate answer, add the goal or location to the acronym, open the official site, and verify current requirements before acting. That small step makes the search more precise and helps ensure that the information you use actually belongs to the organization you intended.
Frequently asked questions about NBRC
Is NBRC a medical certification organization?
It can refer to one: the National Board for Respiratory Care in the United States awards respiratory-care credentials. However, NBRC also refers to unrelated organizations, including a neuroscience institute in India and a regional development commission.
What is the official website for the National Board for Respiratory Care?
The official website is https://www.nbrc.org/. Use its credential, examination, candidate-resource, and contact pages to verify current information.
Where is the National Brain Research Centre located?
The National Brain Research Centre is located in Manesar, Haryana, India. Government institute profiles describe it as a centre for neuroscience research and education.
Can anyone apply for an NBRC grant?
No. For the Northern Border Regional Commission, eligibility depends on the current programme rules, applicant type, project, and designated service area. Review the official applicant resources before beginning an application.
Does NBRC mean the same thing in India and the United States?
No. The National Brain Research Centre is in India, while the National Board for Respiratory Care and Northern Border Regional Commission are U.S.-based organizations with different responsibilities.
How do I make an NBRC search more specific?
Add a clear clue such as “RRT exam,” “neuroscience admissions,” or “Catalyst grant.” Including the location or the full organization name also helps distinguish official information from unrelated results.
A jewelry purchase can begin with a simple goal—find an engagement ring, replace a watch, repair a family heirloom—and quickly become a series of decisions about quality, fit, service, and value. For shoppers searching “new york jewelers Chicago,” the name refers to New York Jewelers, a long-established jewelry and watch retailer in downtown Chicago, not a store in New York City. The business lists its showroom at 11 North Wabash Avenue and says it has operated locally since 1890. [1][2]
The most useful way to evaluate the store is to match its services to the job you need done. New York Jewelers promotes engagement and wedding jewelry, loose diamonds, custom design and in-house manufacturing, new and pre-owned watches, jewelry and watch servicing, appraisals, insurance replacement assistance, and collateral-based luxury loans. Its broad offering may suit someone who wants to compare several categories in one visit, but the right choice still depends on the specific item, written terms, budget, and service timeline.
In brief: New York Jewelers is a downtown Chicago destination for fine jewelry, bridal pieces, watches, custom work, and selected after-sale services. Before making a high-value purchase or leaving an heirloom for repair, confirm the current inventory, exact service scope, price, completion date, return or warranty terms, and any documentation you will receive. This guide explains how to plan a visit, compare options, and ask practical questions so you can make a decision based on details rather than presentation alone.
What Is New York Jewelers in Chicago?
New York Jewelers is an independently owned jewelry retailer in Chicago’s Loop, near the city’s downtown Jeweler’s Row corridor. The company’s published history says it was established in 1890 and describes more than 12,000 square feet of combined showroom space, along with an in-house manufacturing and custom-design center. Those are business-reported details, so shoppers should treat them as the retailer’s own description rather than an independent ranking. [1]
Its showroom is at 11 North Wabash Avenue, Chicago, IL 60602. The official website lists the phone number as (312) 855-4999 and encourages customers to schedule appointments for shopping consultations. Because hours, staffing, inventory, and service availability can change, check the current official website or call before traveling. [1][3]
The phrase “New York Jewelers Chicago” can be confusing because the name includes New York. The business is physically located in Chicago. If you are searching for a New York City jeweler, confirm the address before booking an appointment or ordering online.
Which Jewelry and Watch Services Are Available?
The retailer’s website groups its offerings across jewelry, bridal purchases, watches, and support services. The list below summarizes published categories; it does not guarantee that a particular size, stone, model, repair part, or appointment slot is available on the day you visit. [1][2][3]
| Category | What to explore | Questions to ask |
| Engagement and wedding jewelry | Engagement rings, wedding bands, diamond settings, preset styles, loose diamonds | Can I compare the stone and setting separately? What is included in the final price? |
| Fine jewelry | Rings, earrings, necklaces, bracelets, men’s jewelry and gemstone pieces | What are the metal purity, stone details, and care requirements? |
| Custom design | A personalized piece developed with design and manufacturing support | What are the design, approval, deposit, revision, and final-delivery stages? |
| New watches | Watches from brands the retailer lists as authorized offerings | Is this model in stock, and what manufacturer warranty applies? |
| Pre-owned watches | Previously owned timepieces, including selected luxury brands | What is the condition, service history, included documentation, and return policy? |
| Service and documentation | Jewelry or watch service, appraisals, insurance replacement assistance, and luxury loans | Who performs the work, what is the fee, and what written record will I receive? |
A practical distinction matters: buying a product, commissioning a custom piece, requesting a repair, and borrowing against an item are different transactions. Each should have its own written scope and terms. Do not assume that a policy for a standard online purchase also applies to custom work, altered items, pre-owned watches, or loan agreements.
Is New York Jewelers a Good Place to Shop for an Engagement Ring?
It may be a useful option for shoppers who want to compare loose diamonds with different settings or discuss a custom design. The retailer says it carries hundreds of certified loose diamonds and engagement styles, and that it has more than 2,000 diamond settings available. These are figures published by the business and should be confirmed for current selection and availability. [2]
A productive engagement-ring appointment starts with your priorities, not with a particular display case. Decide what matters most—shape, overall appearance, metal, durability, budget, or the ability to resize the ring later. If you are buying together, discuss whether the wearer prefers a low-profile setting, a prominent center stone, a vintage-inspired look, or a simpler design that fits daily routines.
How should you compare diamonds?
For a diamond, ask for the grading report and compare the familiar 4Cs: cut, color, clarity, and carat weight. A report from a recognized independent gemological laboratory can help you verify the stone’s stated characteristics. The report is not the same as a store warranty, and it does not by itself determine whether a particular diamond is worth the asking price.
Cut and appearance: Ask to view stones in comparable lighting and from more than one angle. A higher carat weight does not automatically mean a diamond will look brighter.
Color and clarity: Compare visible differences with your own eyes, while checking the grading documentation. Do not pay for a grade you cannot explain or do not value.
Setting and wear: Consider prong security, ring height, comfort, and how the design will hold up to daily use.
Total cost: Request an itemized quote that separates the center stone, setting, labor, tax, and any additional services.
If a custom ring is being considered, bring reference photos and explain which elements you like. Ask when you will approve the design, whether a rendering or wax model is included, how many revisions are covered, and what happens if the finished piece differs from the approved specifications. Record stone details, metal type, ring size, delivery date, and any agreed adjustments in writing.
How Can You Compare New and Pre-Owned Watches?
New York Jewelers lists both new watches and pre-owned timepieces. Its published brand information includes authorized new-watch brands and pre-owned examples from makers such as Cartier, Omega, Patek Philippe, and Rolex. Availability varies, so a named brand on a website should not be treated as confirmation that a specific reference is currently in stock. [1][2]
| Check | New watch | Pre-owned watch |
| Condition | Confirm the exact model and whether it is new and unworn | Ask about wear, replaced parts, polishing, and prior repairs |
| Documentation | Confirm box, papers, serial/reference details, and warranty card where applicable | Ask which original documents are included and whether service records exist |
| Warranty | Check the manufacturer’s warranty duration and exclusions | Read the seller’s written warranty and its limits |
| Price comparison | Compare the same model and reference across authorized sellers | Compare condition, age, accessories, service history, and recent comparable listings |
| Resale or trade credit | Ask how future trade credit is calculated | Ask whether any quoted value depends on buying another item |
Before paying, inspect the watch’s reference and serial details where appropriate, check that the paperwork matches the item, and request a written description of condition. For a mechanical watch, ask whether it has been serviced, whether water resistance has been tested, and whether any guarantee covers the movement. A water-resistance rating is not a promise that an older watch remains water-resistant today.
If you plan to trade a watch toward another purchase, ask for two figures: the value offered for your current watch and the price of the new or pre-owned watch before the trade credit. That separation makes it easier to compare offers with another dealer and understand whether the trade is genuinely competitive.
What Should You Know About Repairs, Appraisals, and Insurance?
A retailer with an on-site service center can be convenient for routine work and for discussing a complicated repair in person. New York Jewelers advertises a service center and lists services such as jewelry repairs, appraisals, and insurance replacement support. The precise work accepted, turnaround time, and fee should be confirmed directly before you leave an item. [1][3]
Before leaving jewelry or a watch for repair
Ask for a written intake record that describes the item, visible condition, stones, serial or identifying marks, and accessories left with it.
Request an estimate and ask whether the shop will contact you before performing work that increases the price.
Confirm the expected completion date and how you will be notified if parts or specialist work cause a delay.
Ask what the repair warranty covers, how long it lasts, and what situations are excluded.
Photograph the item and retain the receipt or service ticket until you have inspected the completed work.
For an appraisal, clarify its intended purpose. An insurance replacement appraisal, a resale estimate, and a value used for estate planning are not interchangeable. Tell the appraiser how the document will be used and ask what methodology, item description, photographs, and qualifications will appear in the report. Insurers may have their own documentation requirements, so check with your insurer before commissioning the appraisal.
Insurance replacement assistance is also different from an insurance company’s decision about a claim. Ask who communicates with the insurer, what information is needed, whether you can choose the replacement, and whether any fees or limitations apply.
How Do Luxury Loans Against Jewelry or Watches Work?
New York Jewelers promotes a Luxury Loans service involving cash loans secured by fine jewelry or watches. A collateral loan is not the same as selling an item: the customer receives funds under an agreement and the item is held as security. The contract, not the marketing description, determines repayment obligations and what happens if the loan is not repaid. [1]
Before accepting a loan, ask for the complete written agreement and make sure you understand:
The principal amount you will receive and every fee or charge.
The interest rate, how it is calculated, and the total amount due by the repayment date.
The due date, renewal or extension rules, and any grace period.
How the item is described, valued, stored, insured, and returned after repayment.
The exact process and consequences if you miss a payment or cannot repay.
If your goal is to sell an item rather than borrow against it, request a separate outright purchase offer. For either transaction, comparing more than one written offer is a sensible way to understand the market. Do not hand over a valuable item until you have read the terms and received documentation identifying it.
What Is the Best Way to Plan a Visit to New York Jewelers Chicago?
The store is in Chicago’s Loop at 11 North Wabash Avenue. Its official site recommends appointments for shopping consultations, and its appointment page says valet parking is available in front of the building. Confirm the latest details before setting out, especially if you are traveling from outside downtown or need a specific specialist. [1][3]
| Before the visit | Why it helps | What to bring or prepare |
| Set a budget range | Keeps comparisons focused and helps avoid mismatched options | A comfortable target and a firm maximum |
| List your priorities | Makes the consultation more efficient | Preferred metal, stone shape, watch model, or repair goal |
| Gather existing records | Helps establish ownership, specifications, or prior service | Receipts, grading reports, warranty cards, appraisals, service records |
| Book the right appointment | Allows staff to prepare for a specific need | Explain whether you want bridal advice, a watch consultation, an appraisal, or a loan discussion |
| Confirm terms in advance | Reduces surprises at checkout or collection | Ask about fees, deposits, lead times, returns, and required identification |
For a focused engagement-ring appointment, ask whether the consultant can prepare a range of stones and settings within your budget. For a watch visit, provide the brand and reference number if you have one. For a repair, describe the problem and ask whether the item needs to be left for inspection. A little preparation makes it easier to use the appointment for meaningful comparisons rather than basic fact-finding.
How Should You Evaluate Price, Policies, and Customer Experience?
A luxury showroom can offer selection and specialist support, but those benefits do not remove the need to compare terms. Look beyond the display price and ask for the full cost of ownership: taxes, sizing, maintenance, warranty coverage, insurance documentation, and potential return restrictions.
Online policies can differ by product type. The retailer’s website publishes purchase and return terms, but special orders, custom-made pieces, clearance items, and altered products may be treated differently from standard merchandise. Read the policy that applies to the exact item before paying, and save a copy of the terms presented at checkout. [4]
Customer reviews can help identify questions to ask, but they are not a substitute for a written quote or contract. Review patterns may reflect different departments and transaction types: buying a new ring, selling a pre-owned watch, and arranging a repair are distinct experiences. When reading reviews, look for specific descriptions of communication, delivery, service follow-up, and how concerns were resolved rather than relying only on a star average.
For a high-value purchase, use this simple decision test:
Can the seller document exactly what is being sold or serviced?
Are the price, taxes, deposits, delivery dates, and return rules clear in writing?
Can you explain the warranty and what it excludes?
Have you compared the offer with at least one credible alternative?
Do you feel you have enough time and information to decide without pressure?
If any answer is no, pause and request clarification. A careful jeweler should be able to explain the item and its terms in language you understand.
Conclusion: Is New York Jewelers Chicago Worth Considering?
New York Jewelers is a long-established downtown Chicago retailer with offerings that span bridal and fine jewelry, custom design, new and pre-owned watches, service work, appraisals, and collateral loans. Its range makes it worth considering when you want to explore more than one category or discuss a personalized piece in person. The strongest reason to visit, however, is a clear match between your need and the store’s current inventory or services.
Go prepared with a budget, specific questions, and any relevant paperwork. Confirm availability and appointment details before traveling, and get the item description, price, timeline, warranty, and transaction terms in writing. Those steps make it easier to judge whether the product and service are right for you—at New York Jewelers or anywhere else.
Frequently Asked Questions
Where is New York Jewelers located in Chicago?
The official website lists the showroom at 11 North Wabash Avenue, Chicago, IL 60602. Call (312) 855-4999 or check the official website before visiting to confirm current hours and appointment details. [1]
Does New York Jewelers offer custom engagement rings?
The retailer advertises custom design and in-house manufacturing support. Ask about design approvals, revisions, deposits, delivery timing, and the final written specifications before commissioning a piece. [2]
Can I shop for pre-owned luxury watches there?
Yes, the retailer lists a pre-owned watch collection. A specific brand or model may not always be available, so confirm stock and request details about condition, service history, included paperwork, warranty, and return terms. [1][2]
Can I get jewelry appraised for insurance?
The retailer advertises appraisal services. Before booking, tell the appraiser that the report is for insurance and ask what documentation is included. Confirm any insurer-specific requirements directly with your insurance provider. [1]
Should I make an appointment before visiting?
The store encourages appointments for jewelry and watch consultations. Booking ahead is particularly useful when you want to compare diamonds, discuss a custom design, or meet with a specialist. Check the current appointment calendar before traveling. [3]
What should I check before selling or borrowing against a watch?
Ask for a written valuation and a clear explanation of the transaction. For a sale, compare outright purchase offers. For a loan, review the amount advanced, fees, interest, repayment deadline, renewal terms, storage arrangements, and consequences of nonpayment before signing.
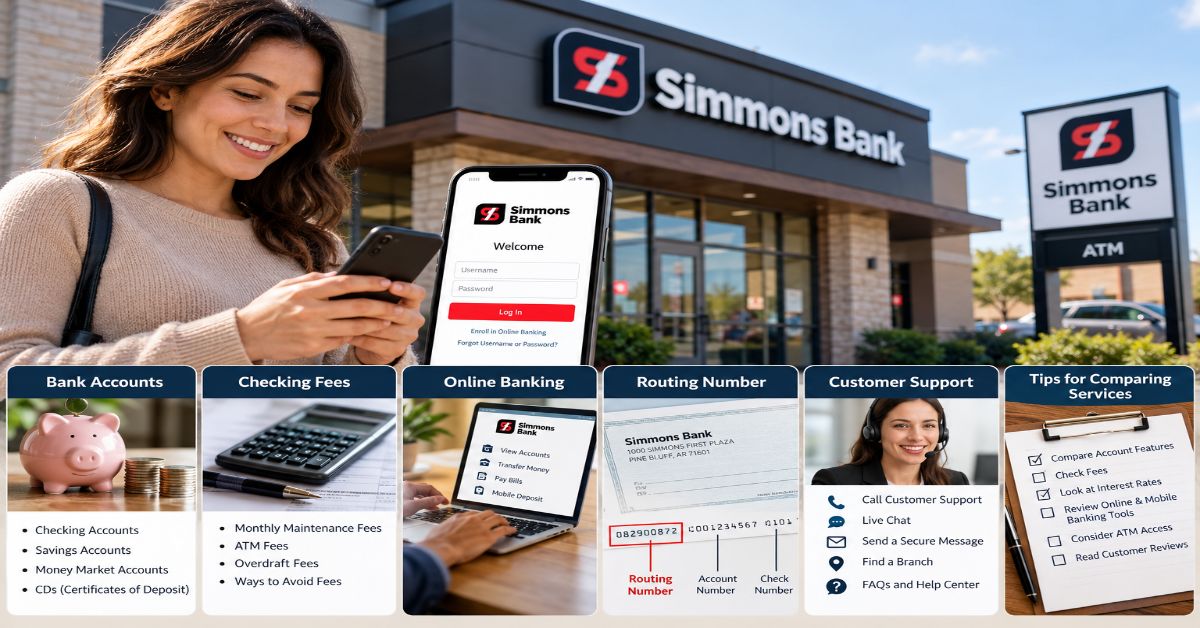
A banking decision often starts with a small, practical question: Can you avoid a monthly fee, deposit a check from your phone, or reach a real person when a card goes missing? Simmons Bank is a U.S. regional bank offering personal and business banking, lending, credit cards, digital banking, and wealth-related services. This guide explains what the bank offers, how its checking options differ, what to know before opening an account, and where to find official support information.
The short answer: Simmons Bank serves customers through branches in Arkansas, Kansas, Missouri, Oklahoma, Tennessee, and Texas, as well as online and mobile banking. Its consumer products include checking and savings accounts, certificates of deposit, money market accounts, credit cards, mortgages, consumer loans, and digital payment tools. Account availability, fees, eligibility, and promotional terms vary by product, so review the current disclosures before applying.
This article is intended for people comparing banks, existing customers who need practical account or login information, and readers checking whether Simmons Bank fits their everyday needs. It uses the bank’s published product and support pages for account details and contact information. It is not a recommendation to open an account: the best choice depends on how you receive income, how often you use ATMs, whether you need branches, and how much you can maintain in the account. Because fees and offers can change, confirm any detail that affects your decision directly with Simmons Bank before taking action.
What is Simmons Bank?
Simmons Bank is a regional financial institution headquartered in Pine Bluff, Arkansas, and a wholly owned subsidiary of Simmons First National Corporation. The bank says it has served customers since 1903 and operates 220 branches across Arkansas, Kansas, Missouri, Oklahoma, Tennessee, and Texas. Its offerings cover everyday deposits, lending, digital services, and business banking. These facts make it especially relevant to people who live or work in its branch footprint, although online tools allow customers to manage eligible accounts remotely.
A branch footprint matters for more than convenience. Customers who regularly deposit cash, need a cashier’s check, or prefer face-to-face help may value a nearby location. Customers who rarely visit branches may focus more on mobile deposit, bill pay, transfer options, ATM access, and account fees. Simmons Bank’s online and mobile services support common tasks such as viewing balances and transactions, transferring money, paying bills, sending money with Zelle, setting card controls, and depositing checks.
Which Simmons Bank accounts are available?
Simmons Bank offers multiple deposit products, but the right account depends on the job you need the money to do. Checking is designed for frequent spending and bill payments; savings and money market accounts are generally intended for money you want to set aside; and certificates of deposit (CDs) typically exchange easier access for a defined term and rate. Read the applicable account agreement and fee schedule rather than assuming that products with similar names work the same way.
The bank’s published checking lineup includes Smart Checking, Signature Checking, Signature Plus Checking, and Private Banking Checking. Names and terms should always be confirmed on the live product page because financial institutions can revise product ranges or eligibility rules. The comparison below summarizes published features, not a guarantee that every applicant will qualify.
How do Simmons Bank checking accounts compare?
The table provides a quick comparison of selected checking accounts and their advertised monthly service charges. “$X or $0” means the stated charge may be waived when the account holder meets the bank’s listed conditions; it does not mean every account is automatically free.
Simmons Bank checking accounts at a glance
Published monthly service charges and selected features differ by account. Confirm current details and waiver conditions on the bank’s official checking page.
| Account | Published monthly charge | Selected features | Best fit to consider |
| Smart Checking | $10 or $0 | No overdraft fee for covered situations; no checks; Early Payday; Round-Up | Customers who want a simple account and can meet a waiver condition |
| Signature Checking | $6 or $0 | Early Payday; credit-score monitoring; Round-Up; check-order discount | Everyday use with several possible fee-waiver routes |
| Signature Plus Checking | $12 or $0 | Earns interest; check benefits; Signature features | Customers who may meet higher deposit or balance thresholds |
| Private Banking Checking | $25 or $0 | Interest and additional private-banking services | Customers who qualify for a broader private-banking relationship |
How can you avoid monthly checking fees?
Simmons Bank lists ways to waive the monthly service charge on several checking products. For Smart Checking, the bank says the $10 monthly charge can be waived by having one direct deposit or one debit-card transaction. Signature Checking lists several potential waiver routes, including qualifying direct deposits, balance requirements, age-based eligibility, or debit-card activity. Signature Plus Checking lists higher deposit or balance thresholds and a military-related waiver. Requirements differ by account, and the bank may revise them.
Before choosing an account, estimate your normal monthly activity rather than relying on a waiver you may struggle to meet. If your income arrives by direct deposit, a deposit-based waiver may be simple. If your balance fluctuates, a minimum-balance requirement may be less dependable. If you use a debit card frequently, a transaction-based option may be practical—but confirm exactly which transactions count.
Paper statements can also add a recurring cost. Simmons Bank’s published checking information lists a paper-statement fee and says enrolling in eStatements can avoid it. Review the disclosure for the specific account you select, because the amount and conditions may differ across products.
What can you do with Simmons Bank online and mobile banking?
Simmons Bank Online & Mobile is designed to let customers manage eligible deposit accounts without visiting a branch. Published features include balance and transaction monitoring, bill payment, transfers between accounts, Zelle payments, credit-score tools, card controls, mobile check deposit, and secure messages. The bank says online and mobile banking use the same login credentials.
A practical first-time setup is straightforward:
Start from the bank’s official website or install the official Simmons Bank app from your device’s trusted app store.
Enroll using the bank’s official enrollment process and the information it requests.
Create a strong, unique password and enable two-factor authentication where available.
Turn on account alerts that help you notice unexpected transactions or low balances.
Review your contact information so the bank can reach you about account security.
Test a low-risk task, such as viewing recent transactions, before relying on the app for an urgent payment.
For check deposits, follow the app’s instructions carefully: photograph the check clearly, enter the correct amount, and retain the check until the bank’s instructions say it is safe to dispose of it. Mobile deposit requires a data connection, and availability can depend on account eligibility, app version, and other restrictions. A submitted deposit is not always the same as immediately available funds, so check the app for any hold or availability notice.
If you cannot sign in, use the official “Forgot?” password-reset option rather than a link in an unsolicited text or email. Simmons Bank lists 1-866-246-2400 for general banking and online-banking support. Never share a one-time security code with someone who contacts you unexpectedly, even if the caller claims to be from the bank.
Can you open a Simmons Bank account online?
Simmons Bank allows eligible customers to open selected accounts online. Its published online-opening information lists products such as Smart Checking, Signature Checking, Signature Plus Checking, Simply Savings, Elevate Money Market, and certificates of deposit, though availability depends on product and eligibility. The bank’s current pages state that online opening for certain accounts is limited to residents of Arkansas, Kansas, Missouri, Oklahoma, Tennessee, and Texas, and that applicants must be at least 18 for the stated online process.
The bank says applicants opening checking or savings online need a valid state-issued ID, a Social Security number, and a computer or mobile device with a camera. A CD application may require additional information and a qualifying opening deposit. Requirements vary by product, and online applications may not support every ownership arrangement. For example, joint ownership or adding beneficiaries may require a branch visit for some accounts.
A sensible application checklist is to confirm that your state is eligible, compare the current fee schedule, gather identification details, and decide how you will fund the account. Read all disclosures before submitting the application. If the online process fails or the identity scan does not work, contact support through the number listed on the official website instead of sending identity documents to an address supplied by an unverified message.
Savings, money market accounts, and CDs
Checking accounts are usually optimized for payments, while savings products are intended to help keep money separate from everyday spending. Simmons Bank lists savings, money market, and CD options among its deposit products. The best fit depends on access needs, the amount you can deposit, the interest rate offered, and any minimum-balance or withdrawal rules. Do not assume a product’s rate or minimum from an older advertisement; verify the current terms on the bank’s official pages.
A money market account may combine interest with some transaction access, but rules can differ from a standard savings account. A CD typically has a set term, and withdrawing funds early may trigger a penalty under the agreement. When comparing products, calculate the likely return after fees and consider whether you might need the money before the term ends. A slightly higher rate may not be worth it if the account’s restrictions do not match your plans.
Deposit insurance is another important consideration. Simmons Bank identifies itself as a Member FDIC institution on its official materials. FDIC insurance generally protects eligible deposits at an insured bank up to applicable limits and ownership-category rules; it does not insure investments such as stocks or mutual funds. For coverage questions, consult the FDIC’s official resources and confirm the account’s legal institution and ownership category.
Loans, credit cards, and business services
Beyond deposits, Simmons Bank advertises consumer lending, mortgages, home-equity lines of credit, credit cards, and business financial services. Business customers may find checking and savings, lending, treasury management, and digital banking tools. The details that matter most—interest rates, fees, repayment terms, credit requirements, collateral, and closing costs—depend on the product and applicant. A headline offer should never replace reading the actual agreement.
For a loan, compare the annual percentage rate (APR), not just the monthly payment. A lower payment can reflect a longer repayment period and a higher total cost. For a home-equity line of credit, understand whether the rate can change, how payments are calculated, and what happens when the draw period ends. For credit cards, check the purchase APR, balance-transfer terms, late fees, and rewards exclusions. Business customers should also ask how account fees scale with transaction volume and whether treasury services have separate pricing.
Simmons Bank’s website provides pathways to contact mortgage, consumer-loan, investment, insurance, and private-banking advisors. If you are comparing offers from multiple institutions, request written terms for the same borrowing amount and duration so the comparison is meaningful.
Simmons Bank routing number and customer service
Simmons Bank publishes routing number 082900432. A routing number is used for certain U.S. payment transactions, but customers should confirm the correct number and instructions for their specific transaction—especially wire transfers, which may have separate instructions. Do not rely on a number copied from an old form or an unverified website when sending money.
The bank’s contact page lists 1-866-246-2400 for general banking questions and online banking, 1-877-245-1234 for 24-hour telephone banking, and 1-800-272-2102 for consumer credit-card service. It also lists separate numbers for business credit cards and lost or stolen cards. Contact details can change, so use the official contact page as the final source before calling.
If your debit card is lost, contact the bank immediately using the number published on its official website or in the verified app. If you suspect fraud, secure your login, review recent activity, report unauthorized transactions promptly, and follow the bank’s instructions. Keep records of the time you reported the issue and any case or confirmation number provided by the bank.
Is Simmons Bank right for you?
Simmons Bank may be worth considering if you live in its regional footprint, want a branch as well as mobile access, or prefer to keep checking, savings, borrowing, and other financial services with one institution. Its online features may also appeal to customers who manage most routine banking from a phone. Those advantages should be weighed against the account’s fee rules, your access to branches and ATMs, and the rates available for savings or borrowing.
Use this checklist before deciding:
Branch access: Is there a convenient location for cash deposits or in-person help?
Fees: Can you reliably meet the waiver requirements, and are paper statements or other services extra?
Digital tools: Does the app support the tasks you actually use, including mobile deposit and alerts?
ATM access: Confirm the network and any out-of-network charges that may apply.
Savings return: Compare current APYs and minimums across competing institutions.
Borrowing costs: Compare APR, total repayment, and fees—not just advertised monthly payments.
Eligibility: Confirm that your location, age, identification, and account ownership needs fit the product’s rules.
A useful way to make the choice is to review one month of your own banking habits. Count how often you use cash, how many payments you make, whether direct deposit is available, and the balance you typically keep. Then compare those facts with the account’s actual terms. This turns “Which bank is best?” into a more answerable question: “Which account costs the least and supports the services I use?”
Conclusion: the key facts about Simmons Bank
Simmons Bank is a long-established regional bank with branches in six states and online tools for routine account management. It offers several checking options, savings and money market products, CDs, lending, credit cards, and business services. The most important decision points are the monthly fee and waiver rules, your eligibility for online account opening, digital features, and the current terms for any deposit or credit product.
For accurate, up-to-date information, start with the bank’s official website, review the relevant disclosures, and contact customer support if a term is unclear. Product names, rates, fees, and eligibility rules can change. Confirming them directly is the safest way to decide whether Simmons Bank fits your financial needs.
FAQs about Simmons Bank
What is the Simmons Bank routing number?
Simmons Bank lists 082900432. Confirm the correct instructions for your specific payment, especially for wire transfers, before sending money.
Does Simmons Bank have online banking?
Yes. Simmons Bank Online & Mobile supports balance and transaction review, transfers, bill pay, Zelle, card controls, mobile check deposit, and secure messages for eligible customers.
Can I open a Simmons Bank account from any state?
Not necessarily. Online opening for selected accounts is limited to eligible applicants in Arkansas, Kansas, Missouri, Oklahoma, Tennessee, and Texas. Confirm current eligibility on the official application page.
Does Simmons Bank charge monthly checking fees?
Some checking accounts have monthly service charges that may be waived when you meet listed conditions. Check the specific account disclosure for the current amount and waiver rules.
How do I contact Simmons Bank customer service?
The bank lists 1-866-246-2400 for general banking and online banking support. For current contact options and hours, use the official contact page.
Is Simmons Bank FDIC insured?
Simmons Bank identifies itself as a Member FDIC institution. FDIC coverage depends on eligible deposit types, ownership category, and applicable insurance limits; consult FDIC resources for your circumstances.
Quick reference: Simmons Bank details
Use this table as a starting point, then confirm current details on the official site before making a transaction or application.
| Need | Published detail | Where to confirm |
| Routing number | 082900432 | Official Contact page |
| General and online banking | 1-866-246-2400 | Official Contact page |
| 24-hour telephone banking | 1-877-245-1234 | Official Contact page |
| Consumer credit cards | 1-800-272-2102 | Official Contact page |
| Branch footprint | Arkansas, Kansas, Missouri, Oklahoma, Tennessee, Texas | Official About and Locations pages |
Official sources and verification
Simmons Bank — About: https://www.simmonsbank.com/about
Simmons Bank — Personal Checking: https://www.simmonsbank.com/personal/checking
Simmons Bank — Open an Account: https://www.simmonsbank.com/open-account
Simmons Bank — Online & Mobile Banking: https://www.simmonsbank.com/personal/digital-banking
Simmons Bank — Contact: https://www.simmonsbank.com/contact
Federal Financial Institutions Examination Council — Institution Profile: https://www.ffiec.gov/npw/Institution/Profile/663245
-
 Guide2 months ago
Voozon.com Guide: What It Is and How It Works
-

 General2 months ago
Spanking Stories: A Reader’s Guide to Themes, Tags and Safer Choices
-
 Technology2 months ago
techtrendery.com: Website Guide for 2026
-

 Technology3 months ago
Coomer.su Explained: Architecture, Data Flow, API Changes and Resilient Client Design
-

 General2 months ago
SABS Framework Description Paragraph: Practical Guide
-

 Technology3 months ago
Listcrawler: How List Crawlers Extract Structured Web Data
-

 Guide3 months ago
How to Run a Marathon: A Practical First-Marathon Guide
-

 General3 months ago
Socialmediagirls Explained: Safety, Privacy, Forum Structure, Leaks and Rules